Company receipt management made easy
From 1 October 2026, business owners may provide their customers with till receipts not only in paper form, but also electronically. The legal bases for this have been adapted in the Federal Fiscal Code (BAO). The aim is to simplify the issuing of receipts in connection with the Cash register to facilitate – without restricting the right to a paper receipt. Below is an overview of what constitutes an electronic receipt and what you should look out for in practice.
What still applies to the electronic receipt?
The following aspects remain unchanged from the previous regulation:
- The receipt must generated immediately in connection with the cash payment become.
- The creation and signing has via the cash register to take place.
- The receipt is for the service recipient to make available immediately.
The electronic receipt thus does not replace the checkout process, merely the form in which the receipt is issued.
How may an electronic receipt be transmitted?
What is new is that the electronic receipt can be transmitted directly to the customer's sphere of control or made available on-site for digital collection. To put it a bit more concretely – permitted forms are, for example, email (text or attachment), app (e.g. customer or checkout app), web download as a PDF or text file, or a structured file format, e.g. XML. No specific technical form is prescribed. It is important to note that the method of issuing the receipt (e.g. email, download, screen display) must be documented in the electronic recording system.
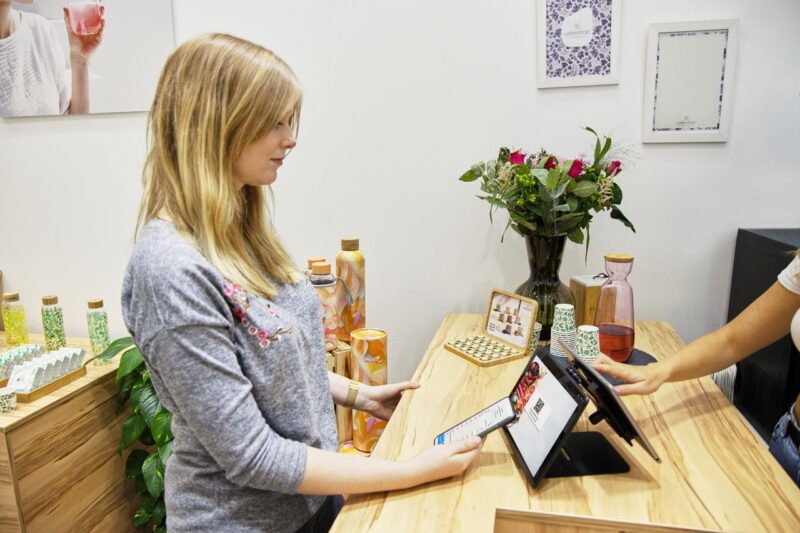
Digital receipt collection on-site | Screen display
Instead of active transmission (e.g. email), the electronic receipt can also be provided directly on-site so that customers can „take it with them“ using their own device. The following applies:
- The receipt is to be displayed on a customer-facing screen.
- The display duration must be sufficient to be able to photograph or scan the receipt during the payment process.
- Digital collection should be possible without changing location – meaning directly at the checkout, without any extra trips.
This means that issuing the receipt remains the responsibility of the company: the receipt must be provided in such a way that customers can easily and immediately accept it.
Right to a paper receipt
Despite electronic options, paper receipts remain equivalent to digital receipts. Customers and tax authority bodies always have the right to request a paper receipt. They may do this immediately after cash payment or until the close of business on the same day.
If the paper receipt is requested later in the day, the essential details of the transaction must be known, in particular:
- Amount of cash payment
- Date and time
- Commercial description of the service or goods
What should companies do now?
As the regulation enters into force as early as 1 October 2026, timely preparation is recommended, in particular:
- Check the point-of-sale systemCheck with your till provider in what format electronic receipts (email, app, download, screen display) are technically possible.
- Define processConsider when an electronic receipt is offered by default and how customers can easily request a paper receipt.
- Ensure documentationMake sure that the type of receipt issuance is correctly recorded in the electronic recording system.
- Notify staffTrain your team at the till so that it is clear how the electronic receipt is provided and how to respond to a request for a paper receipt.
If you have any questions regarding the practical implementation of the electronic receipt or the adaptation of your checkout processes, we at Moore Salzburg are happy to support you – from legal classification to implementation in daily operations.
As of: 17/09/2026
Source: BMF
Photo: Tom Tillhub